
Card issuing
Guides to card issuing: issuer processors, virtual and debit cards, and the bank behind each program.

Instant card issuance: a virtual-first launch guide
How virtual-first card programmes handle holders, controls, PCI scope and physical fulfilment.
Card issuing vs acquiring: issuer, acquirer and interchange
The issuer serves the cardholder, the acquirer serves the merchant, and interchange flows between them.
Issuer processor vs payment processor: who does what
Issuer and merchant processors sit on opposite sides of a card transaction. Here is how the roles split.
BIN sponsorship operating model: roles and controls
How sponsors, program managers, processors and card schemes divide work and control risk.
Commercial card issuing: card types and credit models
Corporate, purchasing and business cards for platforms: who lends, which rules apply and what interchange pays.
BIN sponsorship: how sponsor banks run fintech card programs
Who owns the BIN, who runs the program and who pays for losses when a bank sponsors a card program.
Fleet card issuing: fuel cards vs network fleet cards
How trucking software platforms build fuel and fleet card programs on bank issuers and modern processors.
Card issuing platforms compared: 10 issuer processors
What ten card issuing platforms publish about card types, networks, regions, banks, pricing and API docs.
Debit Card Issuing: How to Launch a Program
The bank, network, processor and program manager behind a debit card, plus the Durbin cap and Regulation E.
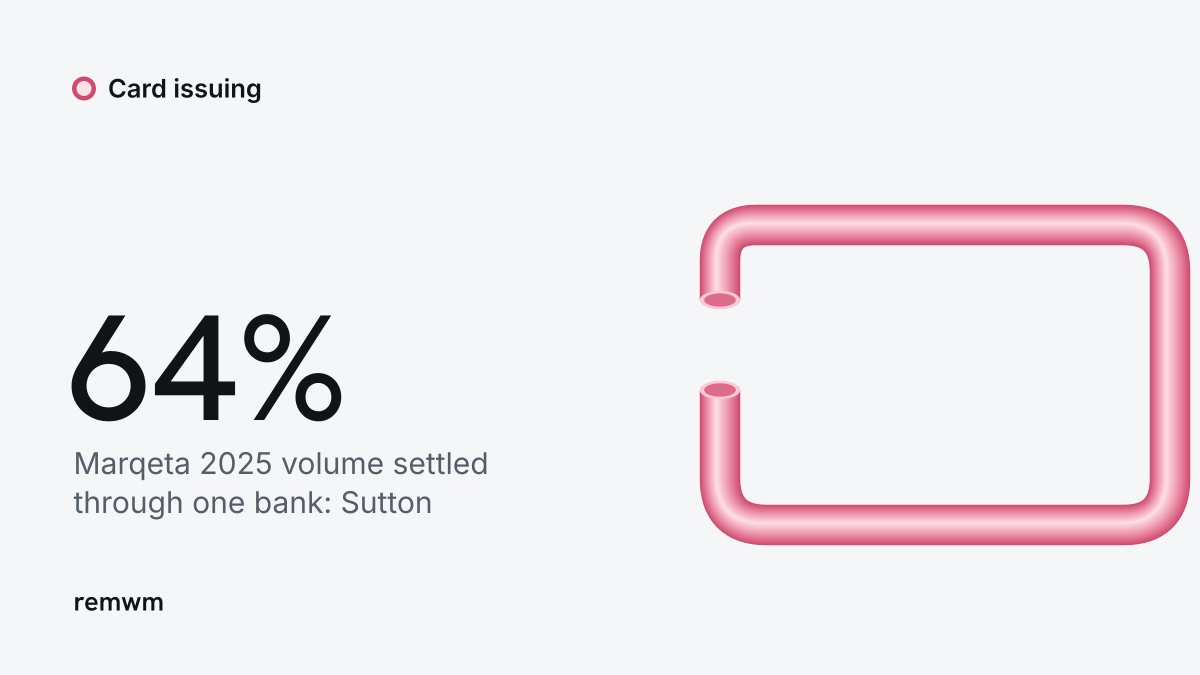
How to choose an issuer processor
Authorization windows, networks, bank partners, uptime evidence and exit terms decide which issuer processor fits.
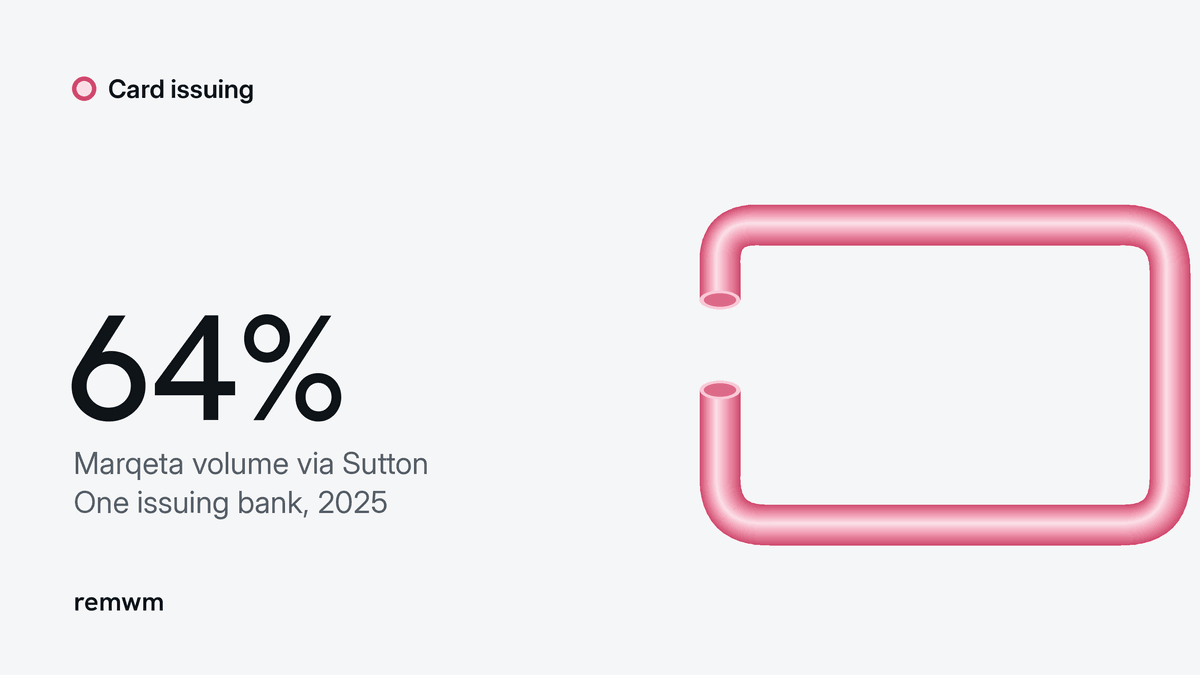
Virtual Card Issuance: How Programs Work
Who issues a virtual card, how each number is controlled, and which US rules apply to consumer and business programs.
A card program has four parties: the issuing bank, the card network, the issuer processor and the program manager. BIN sponsorship explains what the sponsor bank keeps, what the program manager runs, and the FBO and shared-BIN models banks offer. Debit card issuing walks through a launch and the Durbin interchange cap, and virtual card issuance covers single-use and merchant-locked cards. To pick a processor, read how to choose an issuer processor and the comparison of card issuing platforms. For logistics and trucking software, fleet card issuing covers closed-loop fuel cards, Visa Fleet and Mastercard Fleet, and what issuing platforms publish on fleet controls and data. For business programs, commercial card issuing covers corporate, purchasing and business cards, prepaid, charge and credit models, and Visa commercial interchange. Profiles of Marqeta, Lithic, Highnote and Thredd sit in the card issuing providers directory.
Questions
What does an issuer processor do? It authorizes and records card transactions for the issuing bank’s program, under the card network’s rules.
Who issues the card? A bank that is a member of the card network, often called the BIN sponsor; the fintech runs its program under that bank.
What does a program manager do? It runs the program for the bank: customer checks, fraud and disputes, card production and support, usually under a program management agreement.
What is a fleet card? A commercial card for fuel and vehicle spend with controls such as fuel-only purchase types and driver or odometer prompts.
Where is card issuing news? In card issuing news.