
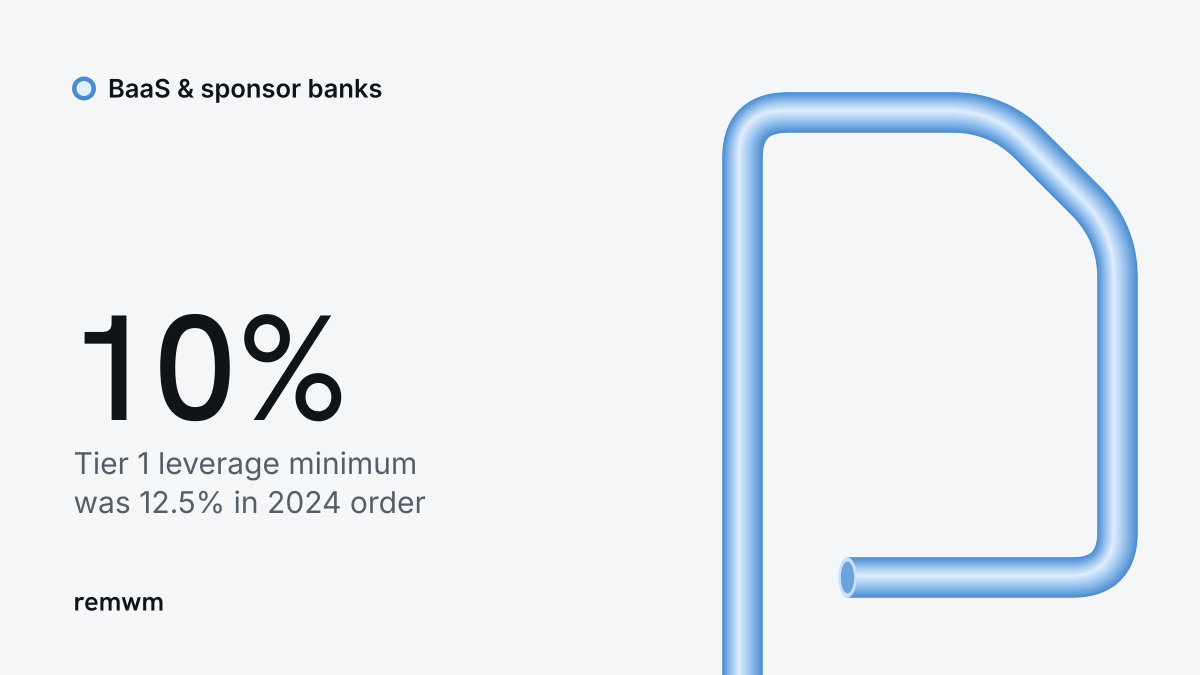
The FDIC published a second consent order for Lineage Bank on July 31, 2026, in its list of June enforcement actions. The order, FDIC-26-0028b, was issued under delegated authority and dated June 24, 2026, and it is in effect as the document shows, with its deadlines running from that effective date. It sets capital minimums, restricts dividends and management fees, and requires plans for brokered deposits and the business.
What the consent order requires
The bank must “maintain its Tier 1 Leverage Capital ratio equal to or greater than 10 percent” and a Total Risk-Based Capital ratio of at least 14 percent, according to the consent order.
Funding and payouts come under supervision with it. The Board must formulate a written “Brokered Deposit Plan” to manage and reduce the volume of traditional brokered deposits, and the bank “shall not declare or pay any dividend or management fees” without the prior written consent of the FDIC’s Regional Director. Within ninety days of the effective date, the Board must provide a business plan covering a three-year period. Lineage’s order is one of 15 the FDIC issued in June 2026, per the agency’s July 31 release.
How it differs from the 2024 order
This is the second consent order for Lineage Bank, a former Synapse partner bank. The first, FDIC-23-0041b from January 2024, dealt with third-party risk in its fintech programs and set higher floors: a Tier 1 Leverage Capital ratio “equal to or greater than 12.5 percent” and a total risk-based ratio of at least 16 percent. The 2026 order lowers both numbers, to 10 and 14 percent, while its subject matter moves to capital, earnings, credit and funding.
What it means for fintech partners
A sponsor bank’s enforcement history does not stop when its program relationships change, and one order can be followed by another on different subjects. A partner reading only the newest document would miss that the capital floors in force today are lower than the ones set in 2024, and that the current order reaches dividends, management fees, brokered deposits and the bank’s three-year plan.
Our profile of Lineage Bank covers the bank, the sponsor bank enforcement actions tracker lists FDIC, OCC and Fed actions since 2023, and how to read a consent order explains the clauses quoted above.
What to watch
The order names one deadline: the three-year business plan, due within ninety days of the effective date. The Brokered Deposit Plan and the two capital ratios are continuing obligations, and nothing in the published documents shows the order has been terminated. Later sponsor bank actions appear in BaaS news.


